Paying Cash Is the Most Expensive Way to Buy
Prefer audio only?
About this Episode
Paying cash is the most expensive way to buy anything. Worse than a loan, worse than a credit card. The man who manages my own money said that to my face, and then he showed me why the dollar you hand over is the only dollar you never get back.
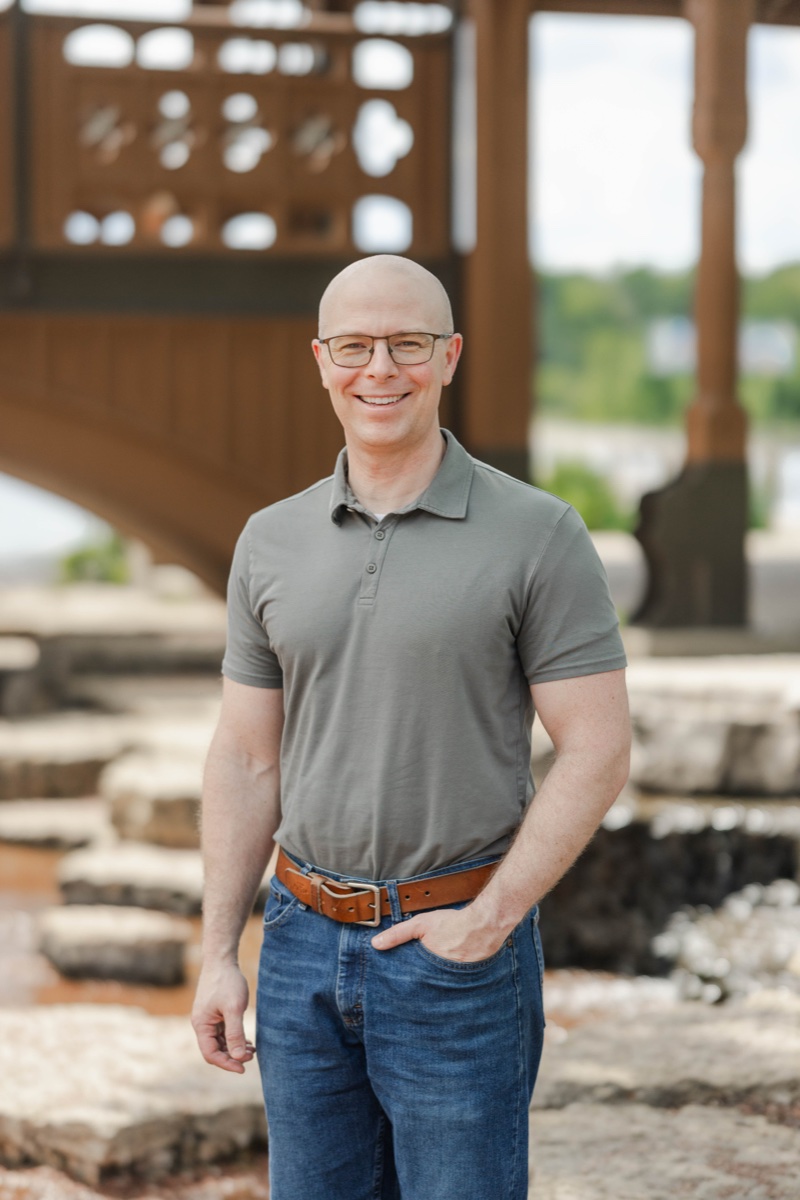
Mark Willis is a Certified Financial Planner, the owner of Lake Growth Financial Services in the Chicago area, and the co-host of the Not Your Average Financial Podcast. He is also my personal wealth manager and today's sponsor, and I say both out loud at the top of the episode. He graduated in 2008 with a master's in divinity, a wife with an arts degree, and six figures of student loans, then spent the recession working three and four jobs, including shoveling out elevator pits, so he could throw every spare dollar at Sallie Mae. He believed every dollar gets spent once and then it's gone. He came on to tell you that rule was never real.
The belief came straight from the radio. Give every dollar a job, pay cash, buy term and invest the rest. Mark followed all of it. The crack came when a college professor sat down at his kitchen table, asked for 45 minutes, and told him he financed everything he bought, including the things he paid cash for. From there we get into why a savings account, a HELOC, and a 401(k) loan all failed his test and whole life insurance didn't, what the median 55-year-old's retirement account produces per month, and the question he says to ask before any financial decision: who besides me benefits from this? I push him on the critics, and he answers. Near the end I put the 2008 version of him across the table with a legal pad and five minutes, and he tells you the first sentence young Mark would have argued with.
Listen to the end. Mark gives a secret phrase on this episode, and I give one on his show later this week. Email both to [email protected] and we'll send you a gift.
Connect with Mark: Website: lakegrowth.com Podcast: nyafinancialpodcast.com LinkedIn: linkedin.com/in/marklakegrowth Email: [email protected]
Every Wednesday I send a free newsletter called What's Real? One lie dismantled, one truth delivered, with the research behind it. Subscribe at therealjasonduncan.com/articles.
Subscribe to What's Real?: https://therealjasonduncan.com/articles Take the Exit Readiness Assessment: https://amireadytoexit.com Get the book: https://exitwithoutexiting.com Book Jason to speak: https://therealjasonduncan.com/speaking The podcast site: https://therealjasonduncanpodcast.com
This episode is sponsored by Bank On Yourself. Book a free consultation with Mark at therealjasonduncan.com/bankonyourself.
Full episode page: therealjasonduncan.com/podcast/409
Key Takeaways
- The lie I want to expose is that every dollar can only be spent once and then it's gone forever. The truth is that financial liquidity and uninterrupted compounding are possible simultaneously.
About the Guest
Mark Willis
Guest
Mark Willis, CFP® is a man on a mission to help you think differently about your money, your economy and your future. Mark is a CERTIFIED FINANCIAL PLANNER™, a three-time #1 Best Selling Author and the owner of Lake Growth Financial Services, a financial firm in Chicago, Illinois. As co-host of the Not Your Average Financial Podcast™, he shares some of his strategies for investing in real estate, paying for college without going broke, and creating an income in retirement you will not outlive. Mark works with people who want to grow their wealth in ways that are safe and predictable, to become their own source of financing, and create tax-free income in retirement.
Never miss an episode.
Subscribe to The Real Jason Duncan Podcast on your favorite platform.
Would you believe me if I told you that paying cash is the most expensive way to buy anything?
It's worse than a loan.
It's worse than a credit card.
And the man who manages my own money said that to me to my face.
And then he showed me why the dollar that you hand over is the only dollar you'll never get back.
It doesn't hurt to just talk to somebody who has a different perspective.
It doesn't cost you anything and it might just save you everything.
Welcome to The Real Jason Duncan Podcast.
I am your host.
Of course, my name is Jason Duncan and every guest on the show is here for one reason.
They used to believe something that turned out to be wrong.
And some of them figured it out on their own, and a lot of them had to get knocked on the butt first.
But either way, by the time they sit across the microphone, they know the difference between what's real and what isn't.
And I've come to understand and believe that the lies that do the most damage are the lies that look like wisdom.
They're the ones that everybody repeats, maybe even famous people repeat them, and that they're the ones that you're so sure
that you're so sure about that you never even think to question them.
And what a lie like that does is it builds a cage around you.
And here's why you stay in it.
It's because the cage looks like gold.
It looks like the smart play.
It looks like the good life, the strong marriage, the right way to handle money, the right way to do things.
And nobody walks away from something that looks like treasure.
And that's what this show is about.
Every conversation here is about finding the cage, seeing that the gold was never real, and then walking out.
Now, today's lie is so basic that most people have never heard it said out loud.
Every dollar gets spent once.
You pay the tuition, you buy the truck, you pay down the loan, and that money's done.
It bought the thing.
The gold in this one is that it sounds like discipline.
You spend or save, you can pick one and be responsible.
Your grandmother believed it and she was right about most things after all, right?
But here's the cage.
If every dollar only works once, then every big purchase in your life stops your growth cold and you spent decades starting over.
Now my guest walked out of grad school into the 2008 crash
owing six figures in debt.
And he lived inside that rule harder than most people do.
And he's here to tell you today that the rule was never real.
Now, before we get into this, we're going to do something different on this show than we do on any other.
So pay attention.
At the end of this show, my guest is going to give you a secret phrase.
And I want you to write that phrase down.
And then later this week on Friday on his show, I'm gonna be a guest on his show.
And on that show, I'm gonna say a secret phrase.
And if you listen to both those shows and you e-mail me at [email protected], we're gonna send you a free gift in the mail just for us for listening.
So make sure you stay all the way to the end and listen for the secret phrase on my show and then on his show later.
Well, let me introduce our guest.
Mark Willis is a certified financial planner, CFP.
He's the owner of Lake Growth Financial Services in the Chicagoland area, and he co-hosts the Not Your Average Financial podcast.
He graduated in 2008 with a master's in divinity.
He's got a wife.
who with an arts degree.
So she's she's kind of smart, too.
And six figures of student loans they had and they spent the recession working in property management, figuring out how money actually behaves.
Now, full disclosure, before we go any further, Mark is my personal wealth manager.
He manages my money, my policies that we're going to talk a little bit about today and
He's the sponsor of today's episode and he's the sponsor of the strategy that I use and I talk about all the time.
So I'm a client of his, I'm an affiliate and you're gonna hear the link later in the show.
But that's why he's in this chair.
That's why he's across the microphone.
It's also why I'm going to push on him harder than I would a stranger.
So, Mark, Mark, welcome to the show, man.
Hey, thanks, Jason, for having me on.
What an intro.
I'm already excited to learn what this guy, this guest of yours is going to share today.
I'm excited.
Who is he?
Well, it's you.
I'm going to brag on Mark for just a minute.
This is not part of my notes, but I had the pleasure of speaking at the National Convention for the Bank on Yourself Professionals earlier this year.
And they give away awards.
And I happen to be in the room when they're giving away awards.
And this man, Mark, won every single award up there.
We were standing next to each other as they started the awards.
And every time they'd call an award winner, we're like, okay, congratulations.
And by the third or fourth time, I just stopped saying congrats.
It didn't matter anymore.
But that's how good he is at what he does.
Now, Mark, before we get into this, I told everybody listening that you came here to talk about a lie that you used to believe.
And that's that every dollar can only be spent once and then it's gone.
But you built a whole practice around that, you know, that idea is being false.
So I want to start there.
In your own words, what did you believe about a dollar and where did that belief come from?
And then I guess, how did you, how deep did that go before you started questioning it?
Oh, yeah.
Well, I can tell you.
There's a long history here and you and I both have connections to the Dave Ramsey world.
Dave Ramsey is a famous radio host and financial infotainer.
I don't call him a financial advisor.
He has no licenses to manage people's money.
He only has a radio license, but he has used that radio license like a megaphone to preach something that I thought was a truism in the financial universe and as a certified financial planner,
I never thought I'd be going down this road talking about this least of all on public places like podcasts and more.
But I found myself really stricken by his quote, wisdom, his golden cage, as it were, when I would hear things like, give every dollar a job, live within your means, only pay cash for expenses, pay off your 15 year mortgage as fast as you can, buy term insurance and invest the rest.
These are all truisms that I think would be something that most of us would assent to and say, yeah, that sounds like wisdom.
As it turned out, I started following that path.
I bought the term insurance.
I got three or four extra jobs.
I had envelopes in my stinking wallet.
I worked three or four jobs during the Great Recession when no one was hiring.
Like you said, the property management jobs.
Guys, let's take the veneer off.
I was like in muddy clothes.
under elevators, shoveling out the stuff that you don't want to talk about on a podcast.
But I was in the muck.
Talk about an ego buster.
I mean, that's a great way to start at the bottom of the totem pole, so to speak, in life.
But it was all for the privilege of serving my real master, which was Sallie Mae.
I jokingly say I actually married two women in college, my beautiful wife and Sallie Mae.
Sally was the one that wanted all of our money, and my wife only got the beans and rice.
So we were living under her thumb for many years.
And again, this was during the worst financial crisis since the Great Depression of 100 years ago when we were trying to do our very best to be the responsible little Dave Ramsey soldiers to pay cash for everything, to pay off our debts dutifully.
And then it hit me.
It hit me like a ton of bricks when someone told me, Mark, you finance everything you buy.
And I said, What do you mean by you finance everything?
I thought I was doing the right thing, the Dave Ramsey thing.
And they said, No, you finance everything you buy.
You either pay interest to the bank with the credit cards or the student loans.
In my case, I had all that student loan debt, or you pay cash for that thing and you finance it from your future self.
You pass up the interest you could have earned on that money
had you not bought that car or gone on that vacation and just left it to grow and invest and compound for you instead.
And all of a sudden, all of my high and mighty righteous experience of working the three part-time jobs, the waiter work, the property management work, the accountancy work I was doing, all of a sudden I realized every dollar I was spending on my student loans, the overpayments on all that debt,
was not only lost to me, but all of the dollars that those dollars could have grown to was lost to me forever.
And remember, I'm in my like mid to late 20s at this point, Jason.
So, you know, you have to think every dollar in your pocket is the most valuable dollar you'll ever have again, because you're as young as you'll ever be today for the rest of your life.
And that means you have the most time to let that dollar increase and compound for you today more than you would when you're 70 years old or 80 years old or 90 years old.
So every dollar in my stupid little mid-20s pocket was hundreds of thousands of dollars over your lifetime compounded if you kind of counted up.
I might have owed 120 grand to Sally and her cronies, but that might've been half a million bucks or more.
If you just think about the maybe a million bucks over a long person's compounded life over a reasonable rate of return.
Do you understand what I mean?
I'm talking about compound interest and opportunity cost.
And Jason, that shook me.
I don't know why it shook me so much.
Maybe I'm just a nerd with numbers, but I realized the power of compound growth and the power of compound interest can both work for you or against you.
And I at that moment realized
It had been working against me that I had been like snookered.
I had been hoodwinked by the infotainers of the world, the Dave Shamsies and the rest of them.
I'm sure he's trying to do the right thing, but he didn't give me the most important thing, which is what is it?
What's Warren Buffett's buddy say?
He's Charlie Munger.
He says, never unnecessarily interrupt compounding.
And I was doing that by paying my student loans.
Jason, I would throw several thousand dollars on top of my minimum payment, and all I would get in response was a little notice saying, thank you for your payment.
Thank you for your payment.
Thank you for your payment.
And that felt good for a while, but then I realized these little slips of paper, these receipts, thank you for your payment, was not going to buy my groceries when I was 72 years old.
Those receipts, those thank you for your payment letters are worthless to me now.
They're worse than worthless.
They are a reminder of why paying cash is not the answer.
And it's why I'll never do it again.
So there's my short answer to your comment.
Well, take me to a month during that stretch of time when you and your wife were paying these extra payments and you started to realize this, who told you this?
And what kind of conversations around the kitchen table did you have that made you start believing, oh, we've made a mistake?
It was a conversation.
It was an aha moment.
It was one of those Paul on the way to Damascus kind of moments.
There was no bright and shining light, but it was actually a professor of mine from college who I think maybe he was just feeling a bit guilty having sort of participated in all that student loan debt.
And it's only gotten worse, by the way, since 2008 when I got out of college.
You know, college tuitions have ballooned significantly since then.
But he came to my apartment, he stayed with us for a few days and he said to me, Mark, I have something important I want to talk to you about.
I need about 45 minutes.
Let's devote some time to really discuss this.
And side comment, side note, that's a super wise way to bring up a heavy conversation with someone.
If you're listening to this and you're trying to figure out how to talk to mom and dad about moving into a nursing home, or if you're trying to figure out how to break the big news to your kids that maybe you've got a dreaded disease, God forbid, or some other just important conversation, a great way to do it is to say, Hey, friend or family member that I love, I have something important to talk to you about.
I need about blank minutes to talk to you.
Could we set aside some time to do it?
That's so much better than just dropping the hammer on that topic.
out of nowhere when they're trying to drive down the street or focus on something else.
So anyway, he brought this idea up to me that Mark, paying cash is not the answer and you finance everything you buy and a dollar you spend is not just gone, it's also gone is all the dollars that that might have grown to over your lifetime.
He brought to me opportunity cost.
And that was the big wake up call saying to me, Mark, you got to figure out a better way.
And then just so happened, my professor who had no skin in the game, he was not a financial professional in any way.
He just thought it was the right thing to do.
He showed me bank on yourself and he explained it to me and he walked me through how you can sit on the other side of the banker's desk.
And Jason, do you have any idea how empowering it is to sit on the right side of the banker's desk to not be kissing the ring?
of the banker when you need money.
To be sitting on the banker's side is to say, I'm in control.
I have complete and absolute certainty over my financial future.
That was a refreshing conversation, but it also was sort of a litmus test for my open mind because I immediately said, the Dave Ramseys of the world say dot, dot, dot.
So I started immediately repeating what I had heard and parroting what I had heard on Dave Ramsey's radio show, which is whole life insurance can never be a good idea.
because my professor, amidst all of his other conversation with me and helping me think through opportunity cost, he laid it out that to become your own source of financing, it's a nice idea, but you also need real financial products that you can use in the real world, right?
The real economy.
And the only way to really become your own source of financing and to buy back your debt to become the banker
And to pay off that debt is better than maybe even paying cash for it is to be to buy the debt back from your student loan companies.
And he said the only way to really become your own source of financing is to use an asset called dividend paying whole life insurance.
Something that's been around for 200 years that grows guaranteed that you have liquid access to and can use like a bank.
where you can borrow against it and the cash value in the policy will continue to grow and compound uninterrupted.
Back to Charlie Munger's quote, right?
Uninterrupted compound growth is the eighth wonder of the world.
You should never break compound growth ever if you can help it.
The only way I've since as a CFP been able to find a way to not break compound growth, Jason, is to just use a life insurance policy designed to bank on yourself way, borrow against it.
and use it to make all my major purchases or pay off my debts.
That's what my professor told me.
And at the time of hearing it, Jason, though, I was still stuck in the lie, the lie that I should always get term insurance, invest the rest in the stock market, hope and pray it all works out, pay cash for everything.
Since then, though,
You know, my mind hopefully and slowly over the next six, seven months began to soften and open up.
And I began to see with real numbers, hey, this could actually work.
I could finally break free of my student loans and not only be debt free, which is what Dave Ramsey loves you to scream on his show, but it would help me to become better than debt free.
Jason, I have one last statement then I'll shut up.
What's better than being debt free?
You give up?
Being the bank, being the bank.
is better than being debt-free.
That's when you really have leverage over your financial future.
Well, I mean, you got it.
It took you, as you said, six months, seven months or so to finally crack the total, you know, the surface and get deep into who you are.
How long was it before your wife was with you on this?
What, like 17 minutes maybe?
She was before you?
Yeah, I mean, we were looking into this together, but she was very much like, yeah, we need to do this, Mark.
And I was having a hard time with some of the big hurdles that most people hit, which is why whole life insurance?
Why couldn't this just be a savings account?
Well, if you think about it, I could use my savings account to pay off my debts.
Many people, you build up savings and then you pay off a debt.
That's called the debt snowball method.
And I was thinking, well, maybe I could use other assets besides whole life insurance.
Could I possibly, for example, borrow against my 401k or my brokerage account or my house?
You can borrow against those assets.
Maybe I could do that.
And one by one, I realized that those assets, let's take a house for example.
Many people understand a home equity line of credit.
I could borrow against my house to pay off my student loans and in some way, sort of like bank on yourself, become my own banker in that I
use my line of credit to pay off my student loans.
But what's happened there?
I've really just moved banks.
I moved it from Sallie Mae to Mr.
Cooper, you know, or whatever the mortgage company is that owns my house.
And they have the puppet strings.
They can control the line of credit amount available, the interest rate charge.
They can change that monthly.
You know, it's usually a variable rate, these HELOCs.
And I didn't like that either.
So I was having a hard time thinking, well, how can I use life and what's the difference with life insurance and other forms of borrowing?
And then I realized it's the contract.
The contract is the bedrock of all civilization.
And when you have a contract that says, hey, your wealth in this contract will increase on a guaranteed basis every single year.
And hey, by the way, you have liquid access to borrow against that anytime you want, and the policy will continue to compound as if the loan never happened.
When that contract is written in such a way, Jason, it really wiped clean any other options.
I didn't wanna borrow from anything else to pay off my student loans, and I certainly didn't wanna pay cash and blow all that money forever.
So I was left with whole life insurance is, yes, it's life insurance, but it's really a cash flow management tool.
that helps me manage the entire operation of my household, my business, not just paying off my student loans, but buying my cars, investing in my business, buying real estate, and more and more and more became the centerpiece, you might say, of one's financial life.
I want to talk a little bit about the idea that cash is the most expensive way to buy anything.
So I want to dig into that just a little bit, leaving life insurance out.
I want to just talk about that particularly.
And then of course, life insurance being one of the solutions to fixing the lie.
But before we get there, I want to give you a minute to think about it.
I want to talk to my listeners about something really briefly.
Let's take a quick break to thank our amazing sponsors for making this podcast possible.
You know, before we get back to Mark, I want to do one quick thing.
Every single Wednesday, I send out a free newsletter called What's Real, and it's one lie dismantled and one truth delivered with the research behind it every Wednesday in your inbox.
If you're interested in reading that, go to subscribe at the real Jason duncan.com/articles.
That's the real Jason duncan.com/articles.
Well, today's sponsor is Bank On Yourself.
And yes, it's the thing that Mark has been alluding to over the last several minutes about, well, about what he's doing and what he discovered.
And here's what it is in one sentence.
Bank On Yourself is a way of using a specially designed dividend paying whole life insurance policy as your own private source of financing so that when you need money for a truck or a piece of equipment or a down payment,
you borrow against your own cash value instead of going to the banksters.
And that cash value keeps growing the whole time.
There's no credit check, there's no application, there's no banker deciding whether you qualify.
You set your own payback terms and your money grows on a predictable schedule and it doesn't drop when the market drops.
Now,
I'm not reading this off a sheet.
I'm actually a client.
Mark structures and manages my policies, and I've got an affiliate arrangement with him, which I'd rather you hear from me than find out later.
That's why I'm saying it up front.
Now, if you want to see whether this fits your situation, you can go to the realjasonduncan.com/bank on yourself, and you can book a free consultation with Mark.
That's the realjasonduncan.com/bank on yourself.
And he's a sponsor, very proud sponsor of the show.
Thank you, Mark, for being a sponsor.
And now let's get back to Bart.
Thanks for listening to our sponsors.
Now back to the show.
So Mark, if paying cash is the most expensive way to buy things, then how do we explain to people that are saying, yeah, but like, how is that more expensive than just getting a loan or putting it on a credit card?
Well, yeah, so when you get a loan or put
your big purchase on a credit card, what are you doing?
You're now subjecting yourself to a contract.
Your contract is pay the banker X dollars per month plus interest or what?
Or the banker sends his goons out to your house to repo the car and wreck your life and your credit score at the same time.
So obviously there's some bad news there, but when you pay cash, I'd say it's even worse because
I would much rather be the slave to somebody else's bank than steal from my future self.
Now, there's a joke, and I'm still working on delivering it, Jason.
I'm gonna try my best, all right?
Now, there's a joke that says, Hey, somebody once told me that taking money out of your savings account is stealing from your future self.
But luckily for me, my future self won't be able to afford a lawyer press charges against me.
That's kind of a sad truth because, hey, yeah, if I have 100 bucks in my savings account today and I spend that $100 on something today, well, I got the little doodad, but I lost the $100.
How much interest do you earn on money you took out of your bank account yesterday?
Not much.
Yeah, nothing.
You weren't earning much before you spent the money and now it's zero, right?
After you spend it.
But what do you miss out on?
You miss out on the $500 or the $1,000 or whatever it could have grown to over your lifetime.
And to me, that's money you'll never see again.
At least with a bank debt, with a credit card debt, you can pay that off.
But you'll never, I mean, never get those dollars back.
If you spend them today on an ice cream cone today, you'll lose 25, 35, 50 bucks in your later years.
And what are you going to do
When you're 82 years old and you can't find work anymore, 'cause who wants to hire you now, and you have nothing in your bank account to show for it, and now you gotta buy groceries again.
Your belly's still gonna be grumbling when you're 82, I'm sorry to say it.
And the average American's retirement account balances are meager.
You know, the median 401k balance for a 55 year old, you ready for this, is 135,000 bucks.
Now, that might sound like a lot to somebody, but I'm telling you, that'll turn into about 300 bucks a month of income.
Now, are you ready for that?
Could you live off 300 bucks a month?
You're 55 in this scenario.
The median American's 401k balance who's 55 to 64 years old is 135 grand, generates 300 bucks a month.
Guys, we've blown, that's a retirement crisis.
I don't know what else to tell you, but let me say it this way, you might not have to end up that way.
If you found a way to get uninterrupted compounding on your dollar starting today, you're as young as you'll ever be ever again.
So the best time to plant that tree is right now.
Second best time is today.
Best time would have been when we were born, but second best time is today.
So putting that dollar somewhere where it will never stop compounding ever again, sign me up.
Now that doesn't mean it's without problems.
We can certainly discuss like the limitations, who shouldn't do this.
I don't go into this with rose-colored glasses.
Folks need to know pluses and minuses part of our work when we meet with clients.
Jason, you know this, having done it with me.
We'll try to say, Hey, look, here's the risks.
Here's the gotchas.
Here's where you shouldn't jump into something like this with your eyes shut.
Go in with eyes open.
But for those that are committed and ready to jump into something like this, we'll make sure it's the right fit, and then we're gonna go in to make sure that this thing is yours for life and beyond your life even.
So here's what I keep coming back to, Mark.
You spent years paying down those loans with dollars that never came back, and every one of those payments was, as we said, the responsible move, and every one of them was, of course, the last time you saw that money.
Now, if you multiply that by everybody who's listening, who's done the same thing with a mortgage, a truck, a kid's tuition, that's a lot of dollars gone that only got one job.
I'm not asking whether paying the debt was wrong.
I'm asking what those years cost you.
Like, what did that cost you and what are they costing the people who are still doing it?
Oh, man.
Well, you said the dollars are gone and you're right in some way, but I'd say they're not gone.
They just went to somebody else's retirement.
Who's got the biggest building in your town?
Jason, who's you think downtown buildings there in your town, it's likely a bank.
Banks and insurance companies.
That's right.
Well, that should tell us something, right?
That should tell.
And by the way, banks are some of the biggest purchasers of these tools.
You look at some of the balance sheets, the tier one capital of Bank of America and, you know, pick your bank, right?
JP Morgan Chase and the rest of them.
Tier one capital asset.
The biggest asset allocation is toward a cash value of life insurance.
So, yeah, your question is a good one.
I'd say, you know, finding out, first of all, that that money is gone.
Second, comprehending just where it went and who benefits.
That's a great question.
I think just to ask in general for any financial plan you end up deciding to go with, whether it's mutual funds or real estate or life insurance or combination, who besides me benefits from this decision is a good question to ask yourself, who besides me benefits from this decision?
If I get a credit card, who's benefiting?
If I get a 401k, who besides me is benefiting from that 401k?
I can give you at least six people besides you.
Can you come up with six other people?
I'm talking about money managers, the county, the state, the federal tax system you're going to have to pay into.
We could keep going, right?
There's six people in front of you in line for your 401k money.
So when you spend that dollar to pay off your debts, yeah, you're debt free, but you're
behind the starting line, because now you're a year older or five years older.
I was gonna be debt-free and feel so great calling old Dave on his radio show, but I should have said, I'm debt-free and seven years older, and I'll never see the millions of dollars I'll lose because I paid that debt off the old-fashioned way.
I'm so glad that about halfway through the project of paying off all that debt, my professor introduced me to this concept, and it's been my privilege to get to introduce it to thousands of others around the country.
Well, so let's get, let's dig into that just a little bit.
I don't want to get too far afield here, but if you have the dollars and you're spending that on a truck or whatever, and it's gone to somebody else, the alternative is to put it into a vehicle, no pun intended, that allows that money to be spent multiple times.
Now, for somebody who's never heard this before, and I know a lot of my listeners know this because I've talked about this
A lot because I believe this.
I've been doing this bank on yourself concept since 2019.
So I've been in it a while, but a lot of people have never heard this.
What is the vehicle and why in the world is whole life insurance even involved in this?
Because that doesn't seem to make any sense.
Why would insurance have anything to do with this concept of cash being too expensive?
Exactly.
Yeah.
Why in the world of all things?
I'll be brief about this and if you want to go even deeper, Jason, we can.
I'll leave it up to you.
It's the only asset that you can collateralize that has a guarantee to it.
So collateralize just means borrow against, right?
You can use it as collateral.
I could use my car and use it as collateral to get a loan from somebody.
I could use my house as collateral and get a home equity line of credit.
You know what collateral means.
I could use inventory in my business.
Collateralizing is a very common financial concept.
But life insurance of all things, I mean, again, we could be talking about anything here, but of course, life insurance is guaranteed to pay out when I croak.
And that's a hundred percent certainty that I'm eventually going to graduate from this earth, right?
So borrowing against that asset now gives me something that will never get taken away from me due to some market downturn or somebody, you know, deciding the wrong thing at the bank.
I've seen people's lines of credit get frozen or merged, not because of their own financial problems, but because the bank is going through a merger or something like that.
But life insurance doesn't have any of that problem.
It's contractually guaranteed for life.
And so every single year, when I open up my account statements and my policies, there's a bigger number there, guaranteed.
Now, how hard is it, Jason, how hard is it in the financial universe for a certified financial planner to use the big G word?
Guaranteed.
It's very difficult.
I can't just go around saying the G word, you know, or I could get in trouble.
Guaranteed is a very hard word to use.
But when it's the insurance company, you know, which has some of the biggest buildings in town, using that word, we know that their claims paying ability is guaranteed because they've been around 150 years, some of these companies.
So right through good times and bad times, recessions, stagflation, and the rest, so I know that my asset
which I can collateralize is getting bigger and bigger and bigger every single year for the rest of my life, I can actually start to build a PLAN on that.
When I know that I'm gonna have 1 million bucks or 500,000 bucks or 5 million bucks in my cash value, whatever your numbers are, every plan is different.
But if I know K-N-O-W that I've got a plan to have a certain X dollar amount when I need to tap into it.
I can begin to rest easy for my future and also make a built plan for today to buy that truck next summer or to go send my kid to college when she's 18, etc., etc.
What do you now know that you wish someone had told you 20 years ago?
And why do you think nobody told you?
Don't listen to infotainers thinking that they have your best interest at heart.
I mean, there's a lot of answers to your great question there, Jason.
Why do you think nobody's telling us that?
Well, and that includes this podcast, by the way.
Okay.
I mean, listen to Jason on all other topics because he's incredibly smart and incredibly astute.
That also means don't just listen to his podcast.
It means call Jason, get on his calendar so he can meet you.
You're just another set of ears right now.
If you're not talking to Jason specifically, once you talk to Jason, he'll be able to coach you, give you guidance, give you real advice.
Don't listen to me on a podcast only.
Also, yes, listen, yes, subscribe, please do, but then also get on our calendars.
Don't listen to Dave Ramsey or any of his cronies.
because they're not financial advisors and they don't have your best interest at heart.
That's the advice I'd give someone 20 years younger than me.
And ask yourself, and again, asking yourself the question, who else besides me benefits from the advice I'm hearing right now?
All right, so put the 2008 version of you across the table for now, or you're sitting across the table from a 2008 version of Mark.
You got six figures in the hole, you got a divinity degree.
You're managing somebody else's rental properties.
You're doing everything you, you know, you're doing everything you were told to do the right way.
Now you've got this guy, this old Mark, the young Mark, I guess it were, you know, young Mark, you've got him for five minutes and you have one legal pad.
What do you draw on it?
And what's the first sentence out of your mouth that he's going to argue with?
These are crazy questions, Jason.
Okay, so you said I have a legal pad.
And you got five minutes.
All right.
All right.
And he's 20 years younger than me.
If I harm him in any way, do I get harmed in the future?
It's like back to the future.
No, I'm not going to do anything like that.
Okay, let me think about your great question.
One of the first words out of my mouth, I don't know if it'd be the first, but I'd say who taught you to think that way would be a question I would ask.
The who beside you?
Benefits from your advice you've been given would be another question.
I would want to ask I'd start Asking questions because it it's it's in the question I think that really breaks the mind open the answers I think you taught me this Jason It's the it's the answers that sort of seal seal the mind off or get it combative So, you know, I'd say I'd say, you know, like what's the cost?
What's the real cost of paying cash for your debt?
and
You know, you think that only other people can be the banker?
Well, who taught you that?
You know, why is that so set in stone?
Where's that written?
You know, that you have to put everything at risk in the markets or that you have to just live as a slave in the debt cycle.
Like, who taught you that?
So these would be some of my questions.
Hopefully, you know, my younger, more, you know, stubborn self would be able to break the mind open and hear some of them.
What would he argue with you about?
It'd be the tropes of what you hear on the radio, you know, on these radio infotainer shows.
I don't even know if they're still around anymore.
I know that Dave and his friends are doing podcasts and other things too, but I'd be repeating the same things that I'd heard, buy term and invest the rest.
Okay, what did Americans end up really doing?
We bought term insurance and went out to eat.
So, you know, the advice, we didn't even take it, but guess where it came from?
You know, it came from a marketing pitch from a guy who owned a term insurance agency and sold mutual funds.
So it's a marketing pitch.
So again, it's, we built our, I had a really wonderful friend and you know her too.
She said, she's a financial advisor.
She's part of the groups that you help mastermind.
And she said,
When she had some floods, she found out in her neighborhood, the pipes were built for 100 years ago, but now there's way more neighbors and we've had some big storms lately.
So there was a bursting of the pipe.
And it reminded her that so much of our pipes in our minds are built for 100 year ago advice.
And we just still live with those old pipes in our minds.
So I just want to say to my 20 year old younger self,
rework your pipes now because we're not getting any younger and we need some new advice, new software upgrades for the future.
Yeah.
So what's the cost of staying inside that life for another five years?
And then what's waiting on the other side for someone who decides to walk out?
Well, yeah, you've got the problem of paying cash.
You've got the problem of the calendar, which you're never getting any, you're as old as you've ever been, and you're as young as you're ever gonna be.
So, you know, my grandpa used to say that toilet paper is like life.
You know, the more you use it, the faster it seems to go.
So five years later, you're gonna just be, not just five years older, but you're gonna be compounded poorer.
There's a Simpsons episode.
Have you seen this one where Homer's drinking like vodka and mayonnaise?
Okay, a bottle of vodka and mayonnaise.
And Marge is like, oh, that's terrible.
What about future Homer?
And he takes another swig and says, huh, future Homer sucks to be that guy.
So I don't want to be, you know, like Homer Simpson.
I want to think long range.
I think at least four generations would be ideal if you could begin to think not just five years in the future, but like 500 years.
What's gonna be different about your family tree because you decided to become your own banker, not just whole life insurance.
And by the way, there's a nice kicker for your family when you do pass away.
Just look up what the Rockefellers did to save their family's wealth, not just life insurance, but also training the kids with the money, right?
You don't wanna just prepare a bunch of money for your kids, they'll blow it.
You also need to prepare the kids for the money, and so the Rockefellers did that.
Homer Simpson didn't do that.
Be more like the Rockefellers, be less like Homer Simpson.
All right, before we close, I want to give you one minute and I'm not going to interrupt you.
I want you to tell the world as directly and passionately as you can what the lie is, why they've been believing it, and what the truth actually is.
Go.
Sure.
Okay.
A minute.
Got it.
There's a book called Debt The First 5000 Years by David Graeber.
I don't agree with everything he concludes, but I love the title.
It just proves to me that banks and banking is as core to the human experience as any other human institution like marriage or friendship or any of that stuff.
If banking is that central to human experience and debt is that permanent.
that I want to sit on the right side of the banker's desk.
The lie you've been told is that you're not allowed to sit over there.
The answer is kick the banker out, fire your banker, sit in his chair, make it your desk and become your own source of financing.
Mark, tell people how to find you.
Well, we already said it.
Go to the real Jason Duncan.com/bank on yourself.
That's our best site where you can learn more about this strategy.
You can meet Jason and me.
We can happily answer questions.
And that's the realjasonduncan.com/bankonyourself.
Here's that secret phrase.
Are we ready for the secret phrase?
Yeah, let's do it.
Okay.
Uninterrupted compounding.
All right, there's your secret phrase, folks.
So uninterrupted compounding.
This is on my show, the Real Jason Duncan Podcast today.
This came out on Monday.
His episode or my episode as a guest on his show, the Not Your Average Financial Podcast comes out this Friday, and I'll be giving a secret phrase if you can give both of those in an e-mail that you'll send to podcast.
@therealjasonduncan.com, [email protected].
You send both those phrases and we're gonna send you a free gift in the mail from Mark and for me.
Well, Mark, thank you so much for being here today.
I appreciate it.
And I got one final question.
If someone listening right now is still inside that lie, they're still believing it, that cash really is the better way, what's the one thing you want them to hear before this episode ends?
It doesn't hurt to just talk to somebody who has a different perspective.
It doesn't cost you anything and it might just save you everything.
Mark, congratulations on all your success, what you've discovered and how you're helping so many people break free from that lie.
Well, my pleasure and thank you so much for having me on the show.
Can't wait to return the favor here in a few days.
Well, that's a wrap on today's episode.
If you saw a bar on your cage that you hadn't noticed before, take a minute and send this episode to someone who needs to see theirs.
As always, I'm your host, the real Jason Duncan, and Jesus is King.
We'll see you next time.
We release new episodes every single Monday, so make sure you tune in.
You can find all the show notes, everything from today's episode and more at the real Jason Duncan.com.
If you want to follow Jason, just search the real Jason Duncan on your favorite social media platform or your favorite AI platform.
You'll find him there.
We'll see you next time on the real Jason Duncan podcast.